Indonesia Trading Services: Cross-Border Execution
12 min read
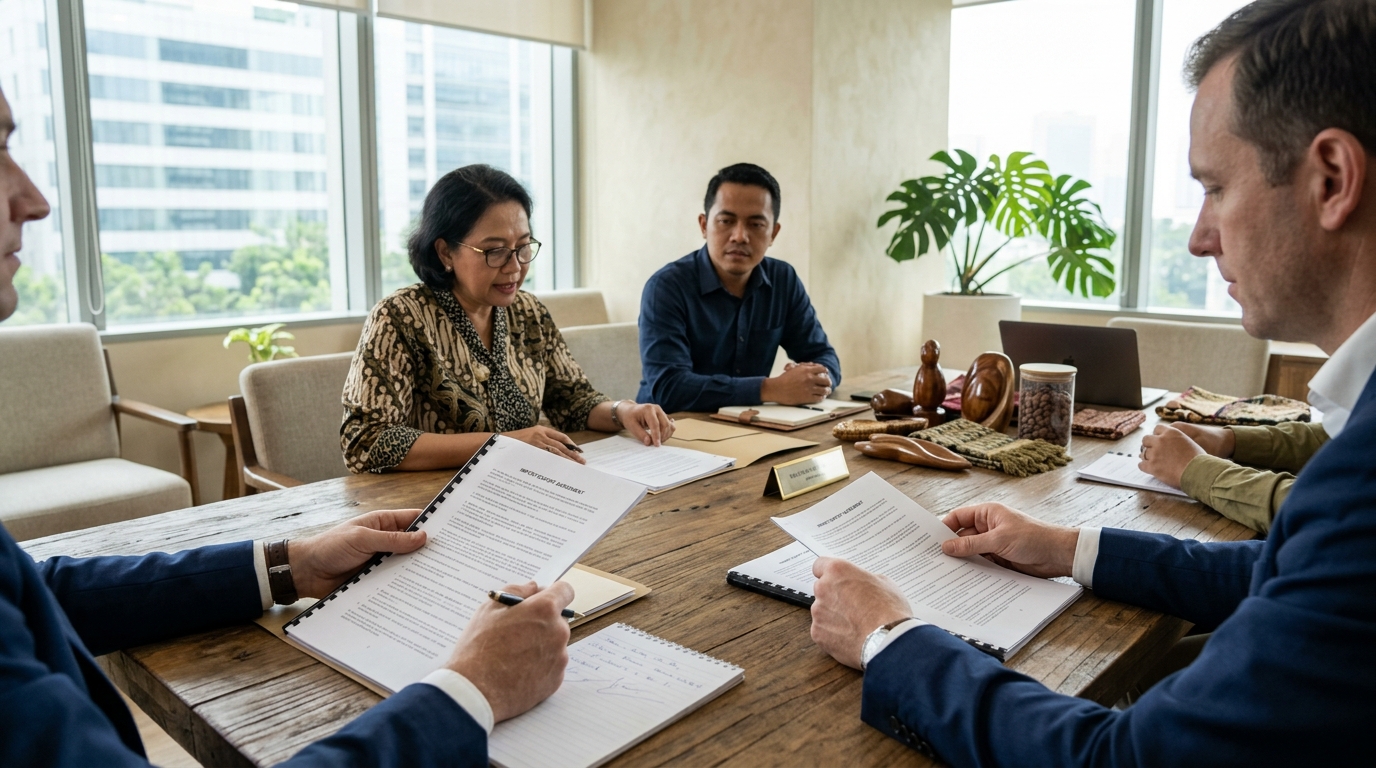
MTS structures Indonesian cross-border trade under a single counterparty contract, managing Rupiah and USD payment flows, LC and TT settlement, VAT treatment on exports, and full documentation from purchase order through final delivery.
Indonesia sits at the intersection of significant manufacturing capacity and growing domestic consumption, making it a two-directional trade corridor for international companies. For procurement managers and brand owners, this creates real opportunity — but Indonesian cross-border trade involves a layered compliance environment that is easy to underestimate. Customs regulations, PPN treatment, foreign exchange rules, and the INSW documentation system all interact in ways that catch buyers off guard when they are dealing with multiple local agents rather than a single structured entity. MTS provides indonesia trading services that consolidate this complexity under one counterparty and one contract, so your team is not chasing confirmations across a fragmented network.
The structural challenge is not unique to Indonesia, but it has specific local characteristics. Indonesian suppliers are often not equipped — or not licensed — to handle export documentation, compliance filings, or USD invoicing directly. Buyers who assume a factory can act as a full-service export counterparty frequently discover that payment terms, VAT treatment, and shipping documentation are misaligned by the time goods reach the port. A trading services layer inserts a qualified, regulated entity between the buyer's purchase order and the factory's production run, ensuring that contracts, payment flows, and customs filings are internally consistent from the start.
This article covers the key structural elements of B2B indonesia trading services: how single-counterparty contracts are structured for Indonesian trade, how Rupiah and USD payment flows are managed, when to use a Letter of Credit versus Telegraphic Transfer, and how PPN — Indonesia's VAT — applies to export transactions. For a broader view of how MTS structures cross-border trading across Asia, see ourInternational Trading Services B2B: One Counterparty for Every Cross-Border Tradeguide.
Why Single-Counterparty Contracts Reduce Risk in Indonesian Trade
When a foreign buyer purchases goods originating in Indonesia, the commercial relationship typically spans a manufacturer or processor, a freight forwarder, a local trading or export company, and sometimes a customs broker. Each of these parties holds a separate contract and carries separate liability. Disputes, delays, or non-conformance become difficult to resolve because responsibility fragments across multiple agreements governed by Indonesian law.
A single-counterparty structure collapses this into one relationship. MTS signs a sale contract with the international buyer — specifying price, quality, incoterms, delivery schedule, and payment terms — and a separate back-to-back supply contract with the Indonesian vendor. The buyer's legal exposure is limited to one contract with one entity. MTS manages the downstream relationships, including production oversight, local freight, and export filing.
This structure is particularly valuable in Indonesia because the regulatory chain from factory floor to FOB or CIF delivery point involves permit verification, PPN treatment, and customs declaration steps that must all be attributed to the same legal exporting entity. If the exporting entity on the Pemberitahuan Ekspor Barang (PEB) does not match the invoicing party, customs can flag the shipment. A single trading counterparty eliminates this mismatch by design.
How Rupiah and USD Payment Flows Work in Practice
Indonesia's foreign exchange regulations, overseen by Bank Indonesia, require that cross-border commercial transactions between residents and non-residents be conducted in foreign currency — typically USD for international trade. This means the international buyer pays MTS in USD, and MTS manages the local Rupiah disbursements to Indonesian suppliers as an in-country operating matter.
This separation has practical advantages. The buyer is not exposed to Rupiah volatility between order placement and payment. The buyer does not need an Indonesian bank account, local tax identification, or relationships with Indonesian correspondent banks. MTS absorbs the currency conversion layer and prices the transaction in USD inclusive of that risk margin.
For buyers who have existing relationships with Indonesian factories and are paying them directly in USD, it is worth auditing whether those suppliers are properly set up to receive and account for foreign currency payments under Indonesian banking rules. Misclassified inflows can create tax and foreign exchange compliance issues for the Indonesian entity, which can surface as supply chain risk for the buyer later.
Payment Timing and Milestone Structuring
In Indonesian manufacturing trade, payment milestones are commonly structured around three points: a deposit on order confirmation, a progress payment at production completion or pre-shipment inspection, and a final balance on bill of lading presentation. MTS structures buyer-facing payment terms to align with these milestones, with the terms specified precisely in the sale contract to avoid ambiguity.
Letter of Credit vs Telegraphic Transfer for Indonesian Transactions
The choice between LC and TT settlement is a function of counterparty risk, transaction value, and goods type — not a preference. For Indonesian trade specifically, the following framework applies:
| Settlement Method | Typical Use Case | Key Consideration for Indonesia |
|---|---|---|
| Telegraphic Transfer (TT) | Established relationships, moderate value, standard goods | Lower bank fees, faster settlement; buyer releases payment against documents or at shipment |
| Letter of Credit (LC) | New counterparties, high-value orders, bespoke production | Documents must match LC terms exactly; Indonesian banks are familiar with LC mechanics but amendment costs accumulate if terms are loose |
| Deferred Payment LC | Long-production-cycle items, buyer prefers extended terms | Usance LC periods are negotiable; aligns payment to buyer's cash cycle |
For buyers using MTS as a trading counterparty, the LC or TT is between the buyer and MTS — MTS then manages its own payment terms with the Indonesian supplier separately. This means the buyer's payment mechanism does not need to align with what the Indonesian factory can operationally handle, which is a meaningful simplification when dealing with smaller Indonesian manufacturers who are not set up for LC administration.
PPN Treatment on Indonesian Exports and What It Means for Your Cost Structure
Indonesia applies PPN (Pajak Pertambahan Nilai) at a zero rate on exported goods. This is a genuine zero rate, not an exemption — meaning the exporting entity can in principle claim back input PPN on domestically purchased inputs used in the production of exported goods. In practice, this mechanism reduces the embedded VAT cost in an export transaction when the supply chain is structured correctly.
For international buyers, the key practical point is that a correctly structured export transaction should not carry PPN on the export invoice. If a supplier is quoting you a price that includes PPN on an export sale, that is a signal that either the supplier is not registered correctly as an exporter, or the transaction is being treated as a domestic sale rather than an export. Both situations create cost and compliance risk.
MTS, operating as the exporting entity, holds the appropriate tax registrations and ensures that export invoices are correctly issued without PPN, while the domestic supply chain from the factory to MTS is managed in accordance with Indonesian PPN rules. This keeps your cost structure clean and avoids PPN liability being embedded in the price you pay.
Navigating INSW, the PEB, and Indonesian Customs Documentation
Indonesia's customs system operates through INSW — the Indonesia National Single Window — which consolidates export and import declarations, permit verification, and duty assessment in one platform. For exports, the key document is the Pemberitahuan Ekspor Barang (PEB). For imports, it is the Pemberitahuan Impor Barang (PIB). Both must be submitted by a registered entity with an active customs identification number.
For goods subject to export restrictions — certain commodities, raw materials, or goods requiring Ministry of Trade or Ministry of Industry permits — the INSW system verifies permit status before the PEB can be approved. Delays at this stage are common when permits have not been obtained in advance or when the commodity description does not match the permit scope.
For regulated imports into Indonesia, import tariff rates and any non-tariff measures can be checked against the Indonesian tariff schedule. Under RCEP and ASEAN trade agreements, preferential duty rates may apply where a valid certificate of origin is presented. MTS manages certificate of origin preparation as part of the export documentation set where preferential treatment is available and relevant to the buyer's import destination.
Indonesian Manufacturing Hubs and Their Trade Logistics Implications
Where a supplier is located in Indonesia affects lead times, export port options, and applicable industrial zone incentives. The major manufacturing corridors for B2B sourcing and trading are:
- Greater Jakarta and West Java (Karawang, Bekasi, Cikarang): Garments, consumer electronics, automotive components, packaged goods. Primary export gateway is Tanjung Priok port in Jakarta. - East Java (Surabaya, Sidoarjo, Gresik): Footwear, furniture, agri-processing, petrochemicals. Tanjung Perak port in Surabaya handles the bulk of East Java exports. - Batam Free Trade Zone: Electronics assembly, precision components, re-export logistics. Proximity to Singapore makes Batam relevant for time-sensitive or high-frequency shipments where Singaporean consolidation hubs are part of the distribution chain. - Bali and Lombok: Handicrafts, textiles, and lifestyle goods for smaller-volume specialty trade.
For a deeper look at supplier landscape and category considerations, see oursourcing from Indonesia hub.
The industrial zone a supplier operates within may also determine whether bonded warehouse or export processing zone rules apply, which affects how and when duties are assessed on inputs and what documentation is required at export. MTS maps these zone-specific rules as part of transaction structuring, not as an afterthought at shipment stage.
How MTS Structures Indonesia Trading Services End to End
For clients using MTS for indonesia trading services, the execution structure follows a consistent sequence regardless of whether the trade is an export from Indonesia or an import into Indonesia.
On the export side, MTS enters a supply contract with the Indonesian manufacturer, manages pre-shipment inspection where specified, files the PEB, arranges freight to the agreed incoterm delivery point, and presents the document set — commercial invoice, packing list, bill of lading, certificate of origin, and any required permits — to the buyer against the agreed payment terms.
On the import side, MTS handles the PIB filing, import duty and PPN calculation, and coordinates with Indonesian customs brokers for clearance and inland delivery. The buyer receives one invoice from MTS covering the landed cost components agreed in the contract.
Both flows are managed under a master trading agreement that covers the governing law, dispute resolution mechanism, and liability framework. This gives the international buyer's legal and procurement teams a single document to review and approve, rather than a stack of local contracts they cannot easily assess. You can review the full scope of MTS trading capabilities at/services.
Structuring Indonesian cross-border trade correctly from the outset — contracts, payment terms, PPN treatment, and customs documentation aligned to one responsible entity — reduces friction at every subsequent stage of the transaction. The cost of getting this structure right at contract stage is substantially lower than resolving a payment dispute, a customs hold, or a VAT audit after goods have moved. MTS provides indonesia trading services designed for exactly this purpose: execution that holds together under the full weight of a real transaction.
Frequently Asked Questions
What is a single-counterparty trading structure and why does it matter for Indonesia?
A single-counterparty structure means one legal entity — in this case MTS — signs the purchase contract with the buyer and a corresponding supply contract with the Indonesian vendor or factory. This eliminates the situation where a foreign buyer holds contracts with multiple Indonesian parties across logistics, trading, and production. In Indonesia, where regulatory obligations, tax identifiers, and customs filings must align with the contracting entity, having one accountable counterparty reduces compliance exposure and simplifies dispute resolution significantly.
Does Indonesia zero-rate VAT on exports, and how does PPN affect our transaction structure?
Indonesia applies PPN (Pajak Pertambahan Nilai) at a zero rate on qualifying exported goods. This means that when goods cross the Indonesian customs border as an export, PPN is not added to the export invoice price. However, PPN is charged at the prevailing standard rate on domestically consumed inputs along the supply chain. Structuring the transaction correctly — ensuring the exporting entity holds the right tax registration and export documentation — is essential to avoid inadvertent PPN liability being embedded in your cost base.
When should we use a Letter of Credit versus Telegraphic Transfer for Indonesian suppliers?
Telegraphic Transfer (TT) is common for established supplier relationships where credit risk is low and transaction values are moderate. A Letter of Credit (LC) is more appropriate for new counterparties, high-value orders, or bespoke manufactured goods where payment should only release against verified shipping documents. In Indonesia, LC issuance typically involves Bank Indonesia's foreign exchange reporting requirements, so the LC terms and document set should be agreed precisely at contract stage to avoid amendment costs or discrepancies on presentation.
How does MTS handle Rupiah versus USD settlement in Indonesian trade transactions?
Most international trade transactions with Indonesia are denominated and settled in USD, which aligns with Bank Indonesia regulations that generally require cross-border commercial transactions to be conducted in foreign currency rather than Rupiah for non-resident parties. MTS invoices the international buyer in USD and manages the local Rupiah disbursements to Indonesian suppliers within the MTS entity, insulating the buyer from local currency volatility and in-country banking complexity. Where Rupiah pricing is used domestically, MTS absorbs the conversion layer.
What customs and documentation system does Indonesia use for import and export clearance?
Indonesia uses INSW — the Indonesia National Single Window — as the primary platform for import and export declarations, permit verification, and customs duty assessment. Export clearance requires a Pemberitahuan Ekspor Barang (PEB), while imports require a Pemberitahuan Impor Barang (PIB). Both declarations must align with the commercial invoice, packing list, and bill of lading. For regulated goods, additional permits from relevant ministries are verified through the INSW system before goods are released or loaded.
Which Indonesian manufacturing regions are most relevant for B2B sourcing and trading?
Greater Jakarta and the surrounding West Java corridor — including Karawang and Bekasi — host a dense concentration of garment, electronics, and consumer goods manufacturers. East Java around Surabaya is significant for footwear, furniture, and food processing. Batam, as a free trade zone adjacent to Singapore, is used for electronics assembly and re-export plays where duty treatment and logistics proximity matter. The region and industrial zone a supplier operates within affects bonded warehouse access, applicable duty structures, and logistics lead times.
Can MTS support both import into Indonesia and export from Indonesia under the same trading structure?
Yes. MTS can act as the trading counterparty for goods moving in both directions. For imports into Indonesia, MTS manages the PIB filing, import duty calculation, and local distribution handoff. For exports from Indonesia, MTS handles supplier purchase contracts, PEB filing, freight coordination, and export documentation including the certificate of origin where required for preferential duty treatment under RCEP or ASEAN trade agreements. Both flows can be managed under the same master trading agreement where the volume justifies it.
Need eyes on the ground in Indonesia?
MTS is an execution partner — supplier verification, manufacturing management, quality control and export logistics across Indonesia, Vietnam and China.
Related services
Related articles
Receive furniture sourcing insights across Asia.
One email per week. No spam.